On this page
Your moving year can contain two tax periodsEstablish the residence start dateAllocate income only after the dates are settledWorked example: a September startOne year does not always mean one declarationThe evidence bundle for a moving yearPrepare for 2027 without assuming its final calendarCommon questionsSources and editorial scopeYour moving year can contain two tax periods
Partial-year residence can split a calendar year into a resident period and a non-resident period. Under CIRS article 15, the resident period brings worldwide income within Portuguese IRS scope. During the non-resident period, Portuguese-source income remains relevant. This is a scope rule, not a promise that every item is taxed or exempt in a particular way.
The first step is to establish whether partial-year treatment applies and its dates. Your arrival, lease, visa and NIF records are evidence, but no single label replaces the tax-residency tests. An earlier visit, residence in the preceding year or a return after departure can change the answer.
Establish the residence start date
CIRS article 16 contains a presence test of more than 183 days in a qualifying 12-month period and a habitual-home test for shorter stays. For those tests, the general start rule is the first day of the relevant period of presence. It is not simply the day you reach day 184 or the day the tax address is updated.
The article also contains exceptions. In particular, someone resident in Portugal on any day of the previous year can be treated as resident from 1 January when the conditions are met again. Departure and reacquisition rules can also lead to full-year treatment. Check them before describing a return as “only the months after I moved”.
Bring the dates together
Use these two records to examine the moving-year questions in this guide. A registered address alone does not answer every residency question.
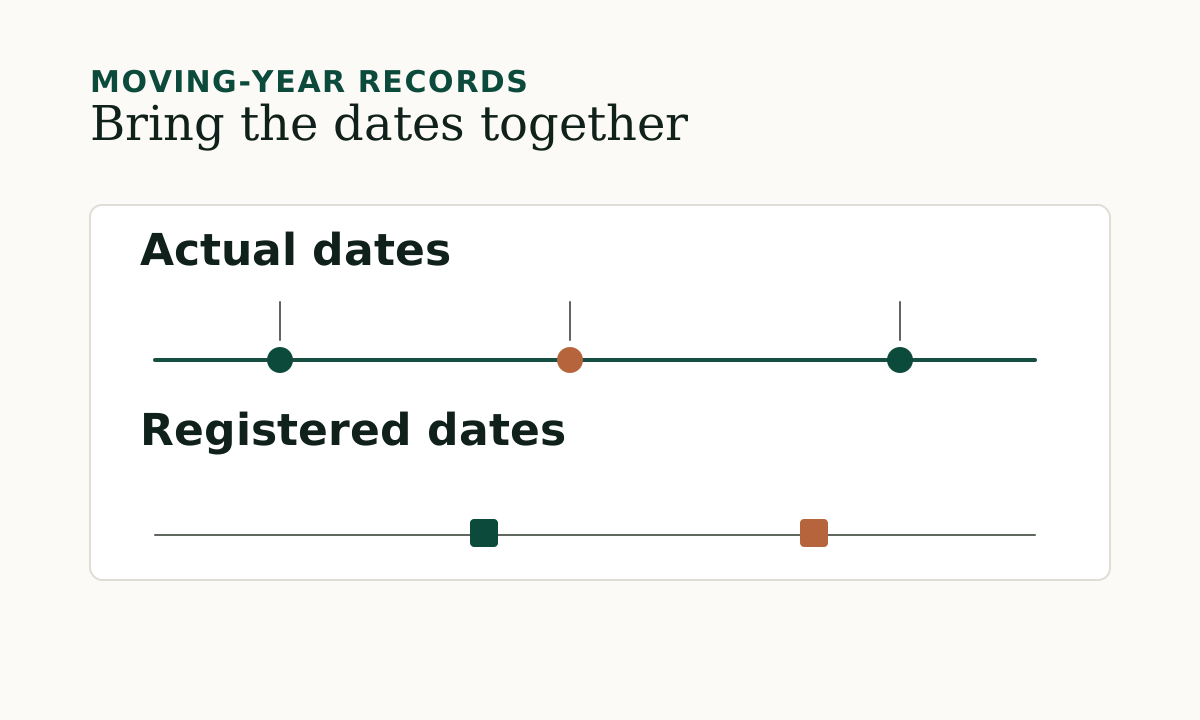
- Your actual timelineTravel dates, overnight stays and when a home became available.
- Your registered timelineThe address and effective dates recorded with the tax authority.
- Write the actual timeline. Include earlier visits, overnight stays, the date a home became available for habitual use and any departure or return.
- Check the previous and following years where relevant. A rolling presence window crosses calendar years, and article 16 includes rules involving adjacent years.
- Compare the registered timeline. Check the address and effective dates in your AT record. Resolve inconsistencies using supporting documents; an administrative date is not a free choice of tax status.
- Check the other country. Its domestic rules may still treat you as resident. If both countries claim residence, examine the applicable treaty rather than assuming the dates meet neatly.
Allocate income only after the dates are settled
Build a worksheet with the income owner, category, source country, relevant dates, gross amount and tax paid. Keep timing and source as separate questions. A bonus for earlier work, deferred compensation or a disposal around the move needs its own analysis; dividing every annual figure by twelve can be wrong.
| Period, if established | Portuguese scope | What to check |
|---|---|---|
| Non-resident period | Portuguese-source income | Any Portuguese rent, work, disposal or other relevant income; filing exemptions and withholding treatment |
| Resident period | Worldwide income | Portuguese and foreign income, relevant dates, treaty treatment and actual regime eligibility |
Worked example: a September start
Assumptions: Mara first comes to Portugal on 1 September 2026 and begins occupying an established habitual home. She had no earlier Portuguese presence in the relevant period, no Portuguese residence in 2025 and no departure/reacquisition complication. Assume the facts support a 1 September tax-residency start and no conflicting treaty conclusion.
1 January to 31 August
Non-resident period. Portuguese-source income still needs to be checked. Do not discard it because Mara lived abroad.
1 September to 31 December
Resident period. Worldwide income falls within scope, subject to its category, timing and applicable relief.
Ordinary 2027 filing window
Prepare the declaration or declarations required for the 2026 periods. Confirm the campaign instructions and any applicable exemption or extension.
Suppose Mara receives €300 interest from a foreign bank during the established resident period. That item prompts a foreign-income check, with account identification considered separately. If she also received Portuguese rent before September, the non-resident-period obligation must be considered too.
This example demonstrates a timeline, not a ruling that every September arrival starts residence on 1 September.
One year does not always mean one declaration
CIRS article 57(6) says that where a taxpayer has two Portuguese residence statuses in the same year, a declaration is submitted for each status, subject to the general possibility of exemption. A resident-period return therefore does not automatically cover every non-resident-period obligation.
Check any exemption under article 58 separately. If only the resident period requires a return, retain the reasoning and supporting records for that conclusion. If both require filing, distinguish the periods and income scopes in the applicable forms.
The first Modelo 3 guide explains the main form and submission steps. The Anexo J guide covers foreign-source income and accounts; it is not a catch-all for everything connected to your former country.
The evidence bundle for a moving year
- A dated travel and overnight-stay record, including earlier visits.
- Lease or ownership documents and evidence of actual habitual-home use.
- AT registration details, effective dates and any correction correspondence.
- Income statements and transaction dates covering both sides of the move, not only the months you expect to declare.
- Work-location records for cross-border employment or services.
- Foreign residence certificates, tax statements and the relevant treaty where dual residence or double taxation is in question.
- Evidence of any special-regime eligibility and applicable application deadlines, checked separately from the return deadline.
For the move itself, use the just-arrived checklist to track your first administrative steps. If your timeline includes a departure, the leaving-Portugal checklist helps you gather the records to review.
The printable first-filing checklist turns these decisions into a practical preparation list. Keep the documents yourself; the checklist does not collect them.
Prepare for 2027 without assuming its final calendar
For 2026 income, the ordinary window under current article 60 is 1 April to 30 June 2027. This guide was checked on 15 September 2026. Confirm the 2027 campaign forms, preparation deadlines and any changes when AT publishes them.
Article 60 also provides a conditional extension for qualifying foreign tax not yet determined, with communication to AT required during the ordinary window. Moving abroad or waiting for a statement does not automatically qualify. Other countries’ returns and any regime registration follow their own rules and timelines.
Common questions
Does my arrival date automatically start tax residence?
No. Establish the article 16 conditions, the relevant period of presence and any exception. Arrival and housing records are evidence for that analysis.
Can my first return ignore everything before the move?
No. If partial-year treatment applies, Portuguese-source income during the non-resident period still needs to be checked. Income timing and any separate declaration obligation must be considered.
Does a late NIF address update delay tax residence?
Not by itself. The underlying facts and legal tests govern the residence analysis. Reconcile inaccurate registered details with evidence through AT.
I moved in November. Can the short period matter?
Yes. The habitual-home test can be relevant before the presence threshold is reached, and rolling day counts can span two years. Establish the position rather than assuming a short first calendar year removes the obligation.
Sources and editorial scope
Sources checked 15 September 2026 by Expatax. This is an editorial check against the linked official material; professional review is not recorded. Examples are fictional and explain the process, not an individual tax outcome.
General information, not personalised tax advice. Your facts and the rules for the relevant income year govern. Check uncertain classifications before filing.